





Your CSRD report, with every figure ready for assurance
Double materiality, ESRS and traceable data in one platform, so your assurance provider can see where every number comes from.


What the CSRD is and what it asks of you
The CSRD is the EU directive on corporate sustainability reporting, Directive (EU) 2022/2464. It replaces the old Non-Financial Reporting Directive and requires a sustainability statement inside the management report, in a common format for the whole Union: the ESRS.
It all starts with double materiality: the impacts your company has on people and the environment, and the sustainability risks and opportunities that affect your results. You only report on what is material, but every data point has to stand up to assurance.
- Regulation
- Directive (EU) 2022/2464, known as the CSRD
- Standards
- ESRS, the European Sustainability Reporting Standards
- Principle
- Double materiality: impact and financial
- Assurance
- Limited, by an independent assurance provider
- Timeline
- The first companies report from financial year 2024; the rest has been postponed
1
Double materiality
You identify impacts, risks and opportunities and decide which topics are material.
2
Data collection
You gather the data the ESRS require for each material topic, with its source.
3
Reporting
You write the sustainability statement as part of the management report.
4
Assurance
An independent assurance provider reviews the report on a limited assurance basis.
What the ESRS cover
E1 to E5
Environment
Climate change, pollution, water, biodiversity and circular economy.
S1 to S4
Social
Own workforce, workers in the value chain, affected communities and consumers.
G1
Governance
Business conduct: ethics, corruption, supplier relationships and political engagement.
Plus, for everyone:
ESRS 1 General requirements
ESRS 2 General disclosures
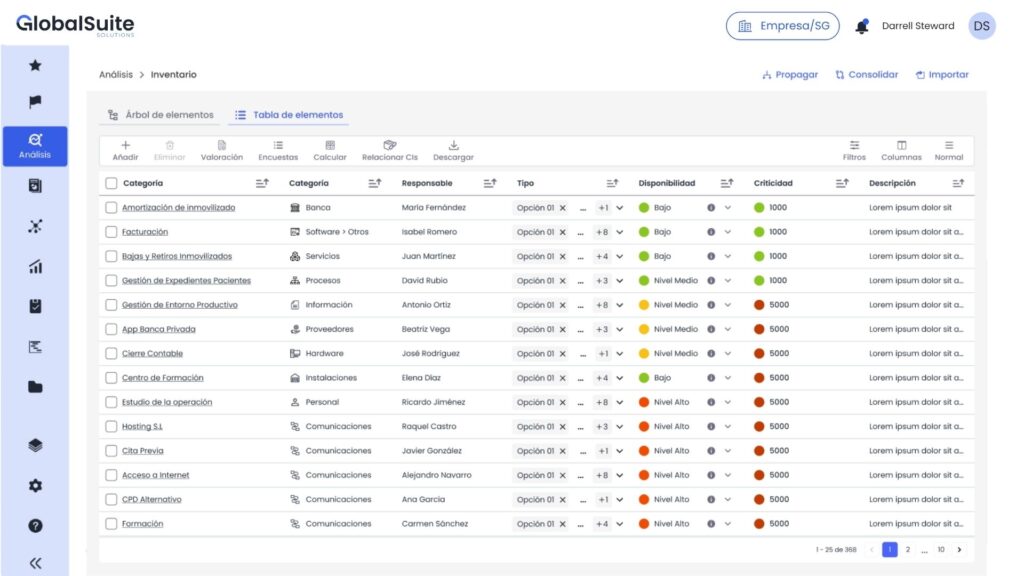
Get ready for the CSRD in GlobalSuite®
From double materiality to the final report in one place, with every data point tied to its owner and its evidence.
ESG›CSRD›Double materiality
Double materiality assessmentCurrent year · 9 of 14 topics material
ESRSTopicMaterialityStatus
E1
Climate change
Scope 1, 2 and 3 emissions
DoubleApprovedE5
Resource use and circular economy
Packaging waste
ImpactApprovedS2
Workers in the value chain
Suppliers in third countries
ImpactIn reviewE4
Biodiversity
No sites in sensitive areas
Not materialJustifiedESG›CSRD›ESRS data
214
Data points collected
38
In review
27
Pending
ESRSDisclosure requirementData collected%
E1-6Gross GHG emissions90
E1-5Energy consumption and mix100
S1-6Characteristics of employees75
S1-16Gender pay gap50
G1-6Payment practices60
ESG›CSRD›Collection by team
Data requests6 teams · 2 running late
RequestOwnerDueStatus
Electricity and gas use by siteDFD. Fuentes15 JanDelivered
Headcount by country and genderICI. Castro20 JanIn progress
Supplier transport emissionsETE. Torres31 JanOverdue
Average supplier payment termsRBR. Blanco31 JanIn progress
ESG›CSRD›Evidence
Evidence for the assurance providerOne piece of evidence per published figure
EvidenceStatusReviewed
Energy bills for all 12 sitesValidtoday
Carbon footprint calculationUp to date3 d
Payroll report for the pay gapPending1 wk
Minutes approving the materiality assessmentFiled2 wk
Every figure, with its source
Each published data point is linked to whoever provided it, how it was calculated and its evidence. It is the first thing your assurance provider checks.
Your value chain, built in
Ask suppliers for the data you need through questionnaires from the third-party risk module.
Year after year
Materiality, owners and data requests carry over to the next reporting year.
The CSRD fits with what you already do
CSRD
Double materiality, ESRS data, collection by team and evidence for assurance.
You are hereESG Management
The GlobalSuite® module for running your sustainability strategy and KPIs.
See solution →Audit Management
Internal audit that checks your data before it reaches the assurance provider.
See solution →Third-party risk
Supplier assessment, essential for value chain reporting.
See solution →
CSRD: frequently asked questions
What is the CSRD?
It is Directive (EU) 2022/2464 on corporate sustainability reporting. Companies in scope must publish a sustainability statement under the ESRS, as part of their management report and with third-party assurance.
Who does it apply to, and from when?
The first wave, large public-interest entities that already published non-financial information, report from financial year 2024. In 2025 the European Union postponed the rest and is reviewing the scope, so it is worth checking which timeline applies to you at any given moment.
What is double materiality?
It means looking at sustainability from two sides: how your company affects people and the environment (impact materiality) and how sustainability matters affect your results (financial materiality). A topic is material if it is material from either side.
What are the ESRS?
The European Sustainability Reporting Standards. There are two cross-cutting standards, ESRS 1 and ESRS 2, and ten topical ones: five environmental, four social and one on governance. You only report on the topics that turn out to be material, except for the general disclosures in ESRS 2.
Who provides assurance on the report?
An independent assurance provider, who reviews the report on a limited assurance basis. That is why every data point needs a clear source and supporting evidence.
Where do I start?
With the double materiality assessment. It tells you which topics you have to report on and, from there, which data you need to start collecting and who to ask for it.
Your CSRD,
ready for assurance.
We will show you your sustainability statement built in GlobalSuite®.